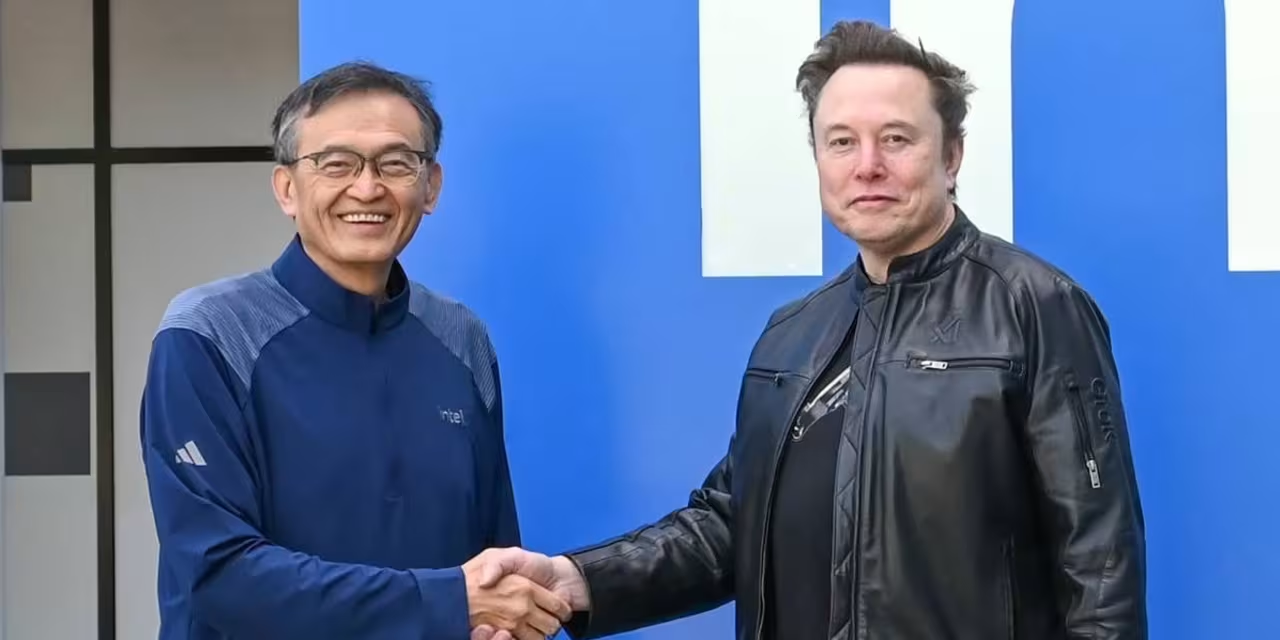
Intel Corp. shares experienced a notable decline this week as the semiconductor giant navigated the fallout from comments made by Elon Musk regarding his future hardware ambitions. The stock market reacted swiftly to the suggestion that Musk, the CEO of high-profile firms such as Tesla and SpaceX, might be leaning toward Taiwan Semiconductor Manufacturing Co. (TSMC) for his upcoming “Terafab” chip venture. While the news sparked a temporary sell-off, analysts are urging a measured perspective on the long-term outlook for the American chipmaker.
What happened
The recent volatility in Intel’s stock price was triggered by social media signals and reports indicating that Elon Musk’s newest ventures into massive-scale chip production—dubbed “Terafabs”—might rely heavily on technology from Intel’s primary rival, TSMC. Musk’s influence in the tech sector means that even a perceived preference for one supplier over another can shift billions in market valuation.
Investors, who have been closely monitoring Intel’s efforts to establish itself as a premier foundry for third-party designers, viewed the potential loss of a high-profile client like Musk as a significant blow. The market’s reaction reflected a fear that Intel’s advanced fabrication nodes might not be moving fast enough to capture the most lucrative contracts in the burgeoning artificial intelligence and aerospace sectors.
Context
Intel is currently in the middle of a high-stakes turnaround strategy under CEO Pat Gelsinger. The core of this plan is the “IDM 2.0” strategy, which involves opening Intel’s factories to outside customers, essentially competing directly with TSMC and Samsung in the foundry business. This is a massive shift for a company that historically only manufactured its own proprietary designs.
To succeed, Intel needs “anchor” customers—large-scale tech companies that require massive volumes of high-performance silicon. Elon Musk’s various enterprises, including his AI startup xAI and the autonomous driving hardware within Tesla, represent exactly the kind of client Intel is courting. However, TSMC currently holds the crown for the most reliable high-volume production of the world’s most advanced 3nd 5-nanometer chips. Musk’s pivot toward TSMC for his Terafab project suggests that, for the moment, the industry leader still holds the technological edge that high-demand innovators require.
Why it matters
While the stock drop is a setback, it highlights the intense pressure on Intel to execute its roadmap without further delays. The competition for semiconductor dominance is no longer just about who can design the best chip, but who can manufacture them at the highest yields and with the most advanced architecture. If Intel can prove its 18A process node is competitive, it may still win over future iterations of Musk’s hardware.
Furthermore, this situation underscores the geopolitical and economic weight of the semiconductor supply chain. With the U.S. government heavily subsidizing domestic chip production through the CHIPS Act, Intel remains a “national champion” in the eyes of many policymakers. The fluctuation in stock price due to a single potential customer, even one as influential as Musk, may be a case of short-term market noise versus long-term industrial shifts.
For investors, the takeaway is not necessarily one of panic but of patience. The battle for the future of the foundry market is a marathon, not a sprint. While TSMC currently enjoys the favor of tech’s most visible figures, the diversification of the global supply chain remains a priority for many firms, leaving the door open for Intel to regain its footing in the years to come.