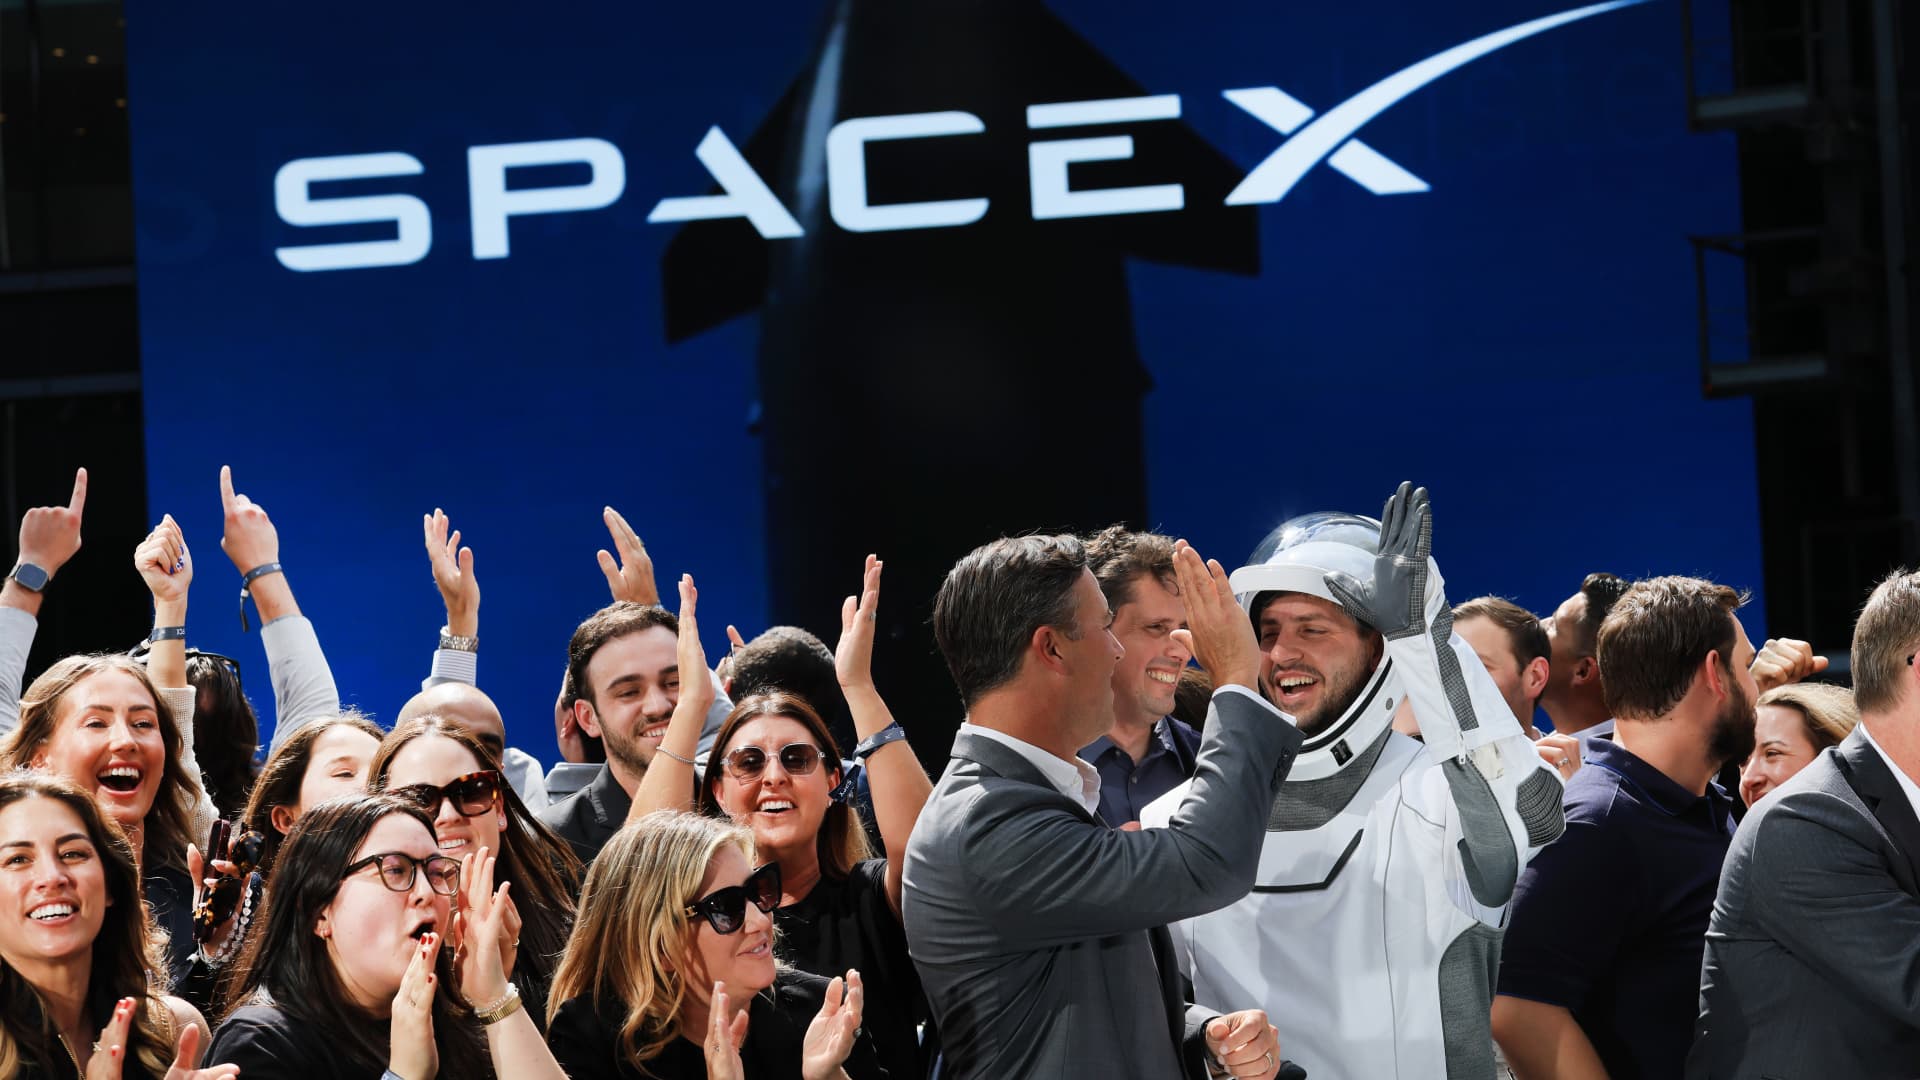
Elon Musk is once again stepping into the spotlight to address the financial community, but the stakes have rarely been higher for his aerospace venture. Just two weeks after Tesla’s quarterly results failed to impress Wall Street, SpaceX is preparing to release its inaugural earnings report as a public company. The report arrives at a turbulent moment for the rocket manufacturer, which has seen its valuation crater since its much-anticipated market debut.
What happened
Since its initial trade on June 12, SpaceX has experienced a staggering decline in market value, shedding over $500 billion in market capitalization. This downward trajectory has been relentless, with the stock recently marking its fourth consecutive week of losses. At its current levels, the share price has fallen more than 50% from its intraday peak, leaving retail investors who bought into the early hype facing significant paper losses.
The scale of this post-IPO slump is virtually unprecedented in the tech sector. While Facebook famously struggled after its 2012 offering, its total market cap at the time was only a fraction of the value SpaceX has lost in the last few months. Adding to the pressure, a rolling lock-up period is set to expire in the coming days. This will allow early investors and employees to sell their shares for the first time, potentially flooding the market with new supply and driving prices even lower. Meanwhile, short sellers have capitalized on the volatility, reportedly netting over $8 billion in profits by betting against the company.
Context
SpaceX’s current financial profile presents a challenging narrative for traditional analysts. Despite its $1.4 trillion valuation, the company’s underlying metrics are stretched. It currently carries a price-to-sales ratio in the 70s—a figure far higher than its mega-cap peers—and is burning through billions of dollars in cash every quarter. Furthermore, the company’s balance sheet shows nearly twice as much debt as it has cash on hand.
The investment thesis for SpaceX remains heavily tied to Musk’s long-term vision rather than current profitability. While the company has established itself as the global leader in rocket launches through its Falcon program, that segment of the business is not yet profitable. Currently, the Starlink satellite internet division is the only part of the company generating a profit. The roadmap for future growth depends almost entirely on the success of Starship, the massive, reusable launch vehicle designed to carry heavier payloads and eventually facilitate the colonization of Mars.
Why it matters
The upcoming earnings call is more than just a financial update; it is a test of investor faith in Elon Musk’s “master plan” for space. For the stock to stabilize, Musk must convince a skeptical market that the high burn rate is a necessary bridge to a future dominated by space-based data centers and global satellite connectivity.
Despite the recent sell-off, some analysts remain bullish. Firms like New Street Research have pointed to the company’s “wide moat” and the revolutionary potential of the v3 satellites and Starship. They argue that for long-term investors, the current dip represents a strategic entry point into a company that essentially has no equal in the private aerospace sector.
However, the shadow of Tesla’s recent performance looms large. With Wall Street already wary of Musk’s timelines regarding AI and autonomous driving, SpaceX will need to provide concrete evidence that Starship’s development is on track to transform the economics of space travel. As the first quarterly report lands, the market will finally get a clearer look at whether SpaceX can transition from a visionary’s dream into a sustainable public powerhouse.